

PORTRAITS OF POWER
WHEN BANKS BECOME A MATTER OF STATE, AND PUBLIC TRUST BECOMES THE MOST VALUABLE FORM OF CAPITAL

By M.Sc. Slobodan TOMIC
Political analyst and publicist, author of the television programme “The Voice of the People”
There are moments when a banking crisis ceases to be merely a financial story and becomes a serious test of a country’s state institutions, political accountability and public trust.
Macedonia finds itself at precisely such a moment.
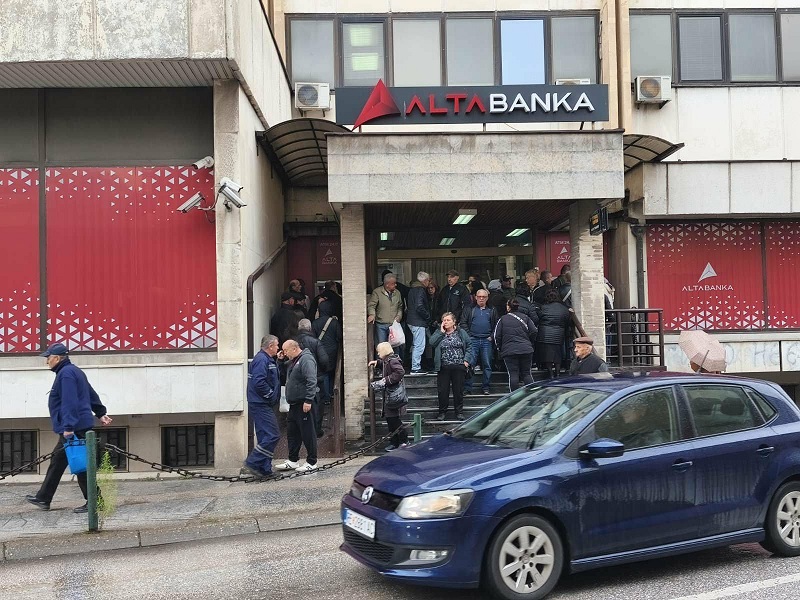
The case of Alta Banka in Bitola is not simply a matter involving one financial institution, one foreign shareholder or one decision by the National Bank. It raises much broader questions: How robust is our system for identifying and controlling banking risks? How effectively do our institutions coordinate their actions? And, above all, does the state genuinely anticipate potential dangers before they develop into problems affecting ordinary citizens?
When a depositor wakes up to discover that access to their own money has been restricted, political explanations, bureaucratic procedures and complicated balance sheets are of little comfort. The questions are straightforward: Where is my money? Who is protecting it? And can I be certain that I will be able to use it tomorrow?
That is precisely why this issue deserves far more than a routine political debate.
ALTA BANKA – WHEN A PARENT BANK’S PROBLEMS BECOME A DOMESTIC BANKING SYSTEM’S PROBLEM
On 1 November 2026, the National Bank of the Republic of Macedonia decided to place Alta Banka AD Bitola under administration.
The decision followed serious institutional and financial difficulties involving its dominant shareholder, Alta Banka AD Belgrade, which held 95.336 per cent of the capital of the Macedonian bank. Following the decision of the Serbian banking supervisor to revoke the parent bank’s operating licence and establish the conditions for initiating insolvency proceedings, the National Bank also withdrew its approval for the Serbian shareholder’s qualifying holding in the Bitola-based institution.
Under the administration measure, responsibility for managing the Macedonian bank was transferred to administrators appointed by the National Bank.
The measure was introduced for a period of three months.
An essential distinction must be made here: placing Alta Banka Bitola under administration does not automatically mean that the bank has entered bankruptcy proceedings or that its operating licence has been revoked.
It is an emergency regulatory intervention intended to protect the bank’s assets, depositors and creditors, while preventing difficulties affecting its shareholder from causing further damage.
But this is precisely where the questions requiring serious institutional answers begin.
How was the risk assessed when Alta Banka entered the Macedonian market from Serbia?
What information was available at the time?
What due diligence procedures were conducted?
Were all the risks associated with the bank’s operations, ownership structure, capital position and the investor’s reputation properly taken into account?
And, most importantly, did the system possess sufficient mechanisms to recognise in advance that problems affecting the parent bank could spill over into a domestic financial institution?
These questions do not constitute accusations. They represent a legitimate public demand for accountability from institutions entrusted with regulatory powers.
The National Bank had an obligation to intervene once the conditions for regulatory action had arisen.
But the public also has the right to ask what happened before the crisis emerged.
Because prevention is more important than intervention.
THE NATIONAL BANK: INDEPENDENCE DOES NOT MEAN FREEDOM FROM ACCOUNTABILITY
The National Bank is one of the most important institutions in the country. Its independence is essential to the stability of the monetary and financial system.
However, independence must never be interpreted as institutional immunity from scrutiny.
An independent institution is not one that is beyond public accountability. It is one that makes decisions free from political pressure, on the basis of law, professional expertise and evidence, and is subsequently prepared to explain its actions.
Governor Trajko Slaveski and the National Bank are now facing a significant institutional test: demonstrating that the measures introduced are lawful, proportionate, time-limited and directed towards achieving the highest possible level of protection for depositors.
One particularly important institutional dilemma emerges from my interview with Kiril Minovski: should the assessment of a foreign banking investor be treated merely as a formal regulatory procedure, or should it involve a broader risk assessment coordinated among all relevant state institutions?
A banking transaction is not an ordinary commercial acquisition.
The National Bank, the Securities and Exchange Commission, the Financial Intelligence Office and other competent institutions all have roles to play, each within the limits of its statutory authority.
The process requires scrutiny of the origin of capital, ownership structures, financial standing, related parties and any risks capable of affecting financial stability.
However, one principle must be emphasised: no institution can be declared guilty simply because an unfavourable outcome subsequently occurs.
What must be established is what the institution knew, what it should reasonably have known, what action it took and whether it fulfilled its legal obligations.
That is the difference between political accusation and institutional accountability.
Macedonia needs independent supervision, but it also needs rigorous scrutiny of the quality of institutional performance.
DEPOSITORS MUST NOT BECOME COLLATERAL DAMAGE OF INSTITUTIONAL FAILURES
One of the most sensitive consequences of the Alta Banka case is the restriction on access to customers’ own funds.
For an ordinary citizen, a salary, pension, savings or family funds are not merely figures on a bank’s balance sheet. They represent years of work, personal security and the future of an entire family.
Whenever the National Bank introduces restrictions, it must provide a clear explanation of why they are necessary, how long they are expected to remain in force and what precisely they are intended to achieve.
An important assessment emerges from my conversation with Kiril Minovski: restrictions may be justified as temporary protective measures, but allowing them to continue without a clear resolution in sight risks deepening public distrust.
Simply telling people that their money is safe is not enough. Citizens need to know when and under what conditions they will regain unrestricted access to their funds.
Particular attention must be paid to pensioners, recipients of social assistance, families meeting everyday financial obligations and companies using these accounts to pay employees and conduct their business transactions.
Restrictions must be proportionate, and access to essential funds must be organised in such a way that the most vulnerable groups are not placed under additional financial pressure.
It is also important to distinguish deposit insurance from uninterrupted access to funds.
The Deposit Insurance Fund provides statutory protection when the legal conditions for activating the guarantee scheme have been met.
For individuals, coverage extends up to EUR 30,000 in denar equivalent, subject to the applicable statutory provisions.
However, while a bank remains under administration and insolvency proceedings have not been initiated, automatic compensation by the Fund does not apply.
There should therefore be no unnecessary panic, but neither should the real difficulties experienced by customers be minimised.
Depositors are not asking for political reassurance.
They are asking for access to their money and genuine institutional security.
SALE OR BANKRUPTCY: WHICH IS THE BEST WAY FORWARD?
The information that potential investors have expressed interest in acquiring Alta Banka is an encouraging development.
On 9 November, Prime Minister Hristijan Mickoski announced that six investors had expressed interest and that discussions had also been held with two domestic banks. According to the announcements, an auction for the sale of the shares is expected towards the end of November or at the beginning of December.
This is an encouraging prospect, but it is not yet a completed transaction.
A clear distinction must be drawn between an expression of interest, a formal bid, the fulfilment of regulatory requirements and the final completion of an acquisition.
The best outcome would be for the bank to secure a new owner who is financially sound, credible and committed to its long-term development.
However, the buyer must not be selected on the basis of price alone.
The prospective investor’s capital adequacy, liquidity, business strategy, experience, ownership structure and capacity to guarantee operational continuity must all be carefully assessed.
If the sale goes ahead, the overriding priorities must be the protection of customers’ funds and legal rights, the uninterrupted provision of banking services and ensuring that ordinary citizens do not bear the consequences of institutional failures.
Bankruptcy should be the last resort, not the desired outcome.
The statutory stabilisation and sale procedures must therefore be given every reasonable opportunity to succeed, free from political interference and without prematurely declaring winners or losers.
EUROSTANDARD BANK: A CASE THAT MUST NOT BE FORGOTTEN
If Alta Banka is today a test of prevention and regulatory supervision, Eurostandard Bank remains one of the most significant tests of institutional accountability in Macedonia’s recent banking history.
On 12 August 2020, the National Bank revoked Eurostandard Bank’s operating licence, after which insolvency proceedings followed.
The bank’s then-owner, Trifun Kostovski, publicly challenged that decision. In several public appearances, he maintained that the bank had deliberately been driven into collapse, that the institutions had acted unfairly and that circumstances requiring further investigation had not been properly examined.
His allegations, particularly those concerning the then Governor, Anita Angelovska-Bezhoska, must be treated as claims made by an interested party, not as established facts.
Nevertheless, they cannot simply be ignored without an institutional response.
In July 2026, the Prosecutor’s Office for the Prosecution of Organised Crime and Corruption announced that it had filed an indictment against three individuals for causing a bank to become insolvent, together with an indictment proposal against one additional individual. Trifun Kostovski is among those charged.
According to the prosecution’s allegations, between 2013 and the second half of 2019, loans were granted to credit-ineligible and related legal entities without adequate financial assessments or sufficient collateral.
The prosecution alleges that the bank’s actual financial position was concealed and that inaccurate information was provided to the National Bank.
The prosecution cited damages amounting to MKD 1,662,417,664, allegedly affecting creditors.
These are serious allegations.
But an indictment is not a final court judgment.
Kostovski has publicly rejected the accusations and maintained that there are no grounds for criminal liability. He is entitled to defend himself, just like every other accused person.
Our position must be principled: no one should be declared guilty in advance, but neither should anyone be declared innocent solely on the basis of a public statement.
The court must examine the evidence.
Yet there is a broader question extending beyond the personal responsibility of bank owners and executives.
When a bank collapses, is it sufficient to establish who managed it, or must the investigation also examine how regulatory supervision functioned, whether risks were identified in time and whether the institutions involved made full use of their statutory powers?
That is a matter of clear public interest.
VENEZUELA, BANCO LATINO AND PARAGUAY: LESSONS FROM THE INTERNATIONAL BANKING EXPERIENCE
Banking crises are not a Macedonian invention. The history of international finance is filled with examples demonstrating how quickly institutional weaknesses can develop into a systemic crisis of confidence.
One of the most significant examples is Venezuela and the collapse of Banco Latino in January 1994.
According to the International Monetary Fund study Banking Crises in Latin America in the 1990s, Banco Latino was Venezuela’s second-largest bank in terms of deposits. As concerns about its financial condition spread, deposit withdrawals began.
The bank attempted to meet the outflows by selling assets and obtaining additional financing, but the situation eventually became unsustainable.
The bank’s closure resulted in the freezing of financial obligations, while uncertainty spread to other institutions.
Subsequent developments included interventions, nationalisations and additional measures intended to protect depositors.
The lesson is clear: a banking crisis does not end with the decision to close one institution. It can spread through fear, declining confidence and the withdrawal of deposits.
There is also a more recent example.
In Paraguay, the case involving digital bank ueno in November 2026 triggered a serious institutional and political crisis. The Central Bank initiated a resolution process following identified problems concerning compliance with minimum solvency requirements.
The case raised questions about regulatory supervision, connections between ownership interests and politics, and the effectiveness of institutional safeguards. The governor of the Central Bank subsequently resigned.
Reuters also reported that the case had significant repercussions on the political scene, including investigations and pressure involving senior government figures.
These examples must not be mechanically equated with the Macedonian situation. The legal frameworks, economic structures, institutional capacities and underlying causes of the crises are different.
Nevertheless, they share a fundamental message: financial stability requires continuous supervision, independence, transparency and a timely institutional response.
The banking sector is part of a country’s critical infrastructure.
Its stability is therefore not merely an economic concern. It is an issue of national security and public confidence.
POLITICAL ACCOUNTABILITY: WHY HISTORY DOES NOT BEGIN WITH EVERY NEW PRIME MINISTER
In Macedonia, political memory is often selective.
Whenever a problem emerges, the opposition immediately seeks to place responsibility on the incumbent government, even when the underlying causes may have developed much earlier.
On the other hand, every government must understand that assuming power also means accepting responsibility for resolving inherited problems.
That is the essence of responsible state leadership.
Hristijan Mickoski has been Prime Minister since 2024.
His government must be held accountable for its own decisions, but it cannot automatically be blamed for every consequence of institutional and economic policies established under previous administrations.
The previous seven years of SDSM-DUI rule deserve serious scrutiny: the Prespa Agreement, energy policies, public procurement, privatisation processes, public financial management and institutional failures.
However, political criticism is not the same as evidence of criminal conduct.
Every suspicion requires investigation.
Every accusation requires evidence.
Every finding of responsibility must follow the law.
What cannot be accepted is selective political justice.
It is unacceptable to demand maximum accountability from one government while remaining silent about questions concerning its predecessors.
Nor is it acceptable to use a banking crisis as a political weapon while overlooking depositors, creditors and the institutions obliged to provide answers.
Equally unacceptable is reducing political debate to insulting personal labels directed at the Prime Minister.
Political criticism is legitimate. Insults are not arguments.
At the same time, the government must demonstrate sufficient confidence to accept scrutiny, explain its decisions and ensure that no institution becomes a politically protected territory beyond accountability.
Statesmanship is not about avoiding responsibility. It is about distinguishing one’s own responsibility from inherited problems and then having the determination to address both.
WHO SUPERVISES THE SUPERVISOR?
This may be the most important question arising from the entire case.
The National Bank supervises commercial banks. But who evaluates the effectiveness of the National Bank’s supervisory performance?
Not in the sense of political interference with its independence, but in terms of institutional accountability, legality and professional assessment.
Are there mechanisms capable of establishing whether risks were identified in time?
Were supervisory procedures adequate?
Did the relevant institutions exchange information?
Were there warning signals that could have been recognised earlier?
These are questions that deserve examination in both the Alta Banka and Eurostandard Bank cases.
If a failure occurred, it must be established.
If no failure occurred, that too must be demonstrated through evidence.
Neither the Governor, the Minister, the Prime Minister nor the owner of a bank can stand above the law.
But none of them should be declared guilty merely to serve a political purpose.
THE BANKING SYSTEM: HOW SAFE IS IT?
According to the International Monetary Fund’s assessment of June 2026, Macedonia’s banking sector is well capitalised and liquid, while the financial system as a whole has been assessed as stable.
This is an important and reassuring finding.
However, that assessment does not mean that risks do not exist or that every individual bank is automatically safe.
The IMF has highlighted the need for careful monitoring of rapid credit growth and increasing exposure to the real estate sector.
In other words, there are grounds to conclude that the banking system as a whole possesses a degree of resilience, but there are no grounds for complacency in regulatory supervision.
An individual bank can experience serious difficulties while the wider banking system remains stable.
However, if institutions fail to respond in time, an individual problem can develop into a broader crisis of confidence.
That is precisely why the distinction between the stability of the banking system as a whole and the financial condition of an individual bank is essential.
Citizens should not panic or withdraw their money from sound banks because of an isolated banking crisis.
But institutions must understand that public confidence cannot be taken for granted. It must be earned every single day.
WHAT MUST CHANGE?
Several essential requirements emerge from this analysis.
First: Full institutional transparency, within the limits imposed by law, particularly concerning the reasons for placing Alta Banka under administration and the subsequent stabilisation process.
Second:An independent and professional review of the procedure through which the foreign investor entered the domestic market, including all relevant documents, assessments and information available at the time approval was granted.
Third: A swift and lawful resolution of Alta Banka’s status, with priority given to the interests of depositors, employees, businesses and creditors.
Fourth: A comprehensive judicial and institutional examination of the Eurostandard Bank case, respecting the presumption of innocence and the right to defence, while remaining firmly committed to establishing the facts.
Fifth: Improved coordination among financial and supervisory institutions, particularly when assessing foreign investors and associated risks.
Sixth: Continuous monitoring of the banking sector, without privileged entities and without political influence.
Seventh: Accountability on the part of everyone entrusted with statutory powers and public responsibilities.
This is not a demand for political retribution.
It is a demand for a functioning state.
THE FINAL WORD: TRUST IS THE MOST VALUABLE CAPITAL A COUNTRY CAN POSSESS
The German philosopher Arthur Schopenhauer is often associated with the idea that trust, once lost, is extraordinarily difficult to restore.
This insight is particularly relevant to banking.
A bank does not operate on capital, loans and deposits alone.
It operates on trust.
Citizens deposit their money because they believe that institutions supervise banks, that the rules apply equally to everyone and that their savings are not dependent on someone’s political or commercial interests.
Once that trust is shaken, the consequences extend far beyond a financial balance sheet.
John Maynard Keynes warned that financial expectations and public sentiment can exert enormous influence on the economy. Managing confidence is therefore an integral part of maintaining financial stability.
Aristotle established a fundamental principle of political wisdom long ago: good governance must be measured by the common good, not by the interests of those who hold power.
That is precisely the point.
Alta Banka must not become yet another case that disappears from public attention after a few weeks.
Eurostandard Bank must not remain merely a subject of political exchanges and judicial proceedings that the public struggles to understand.
The National Bank must be neither a political target nor an institution exempt from accountability.
Trifun Kostovski has the right to defend himself and to have his allegations examined. The prosecution has the obligation to substantiate its claims. The courts have the duty to reach independent decisions. The National Bank has the responsibility to safeguard the financial system. The government has the obligation to create the conditions for effective institutions, while citizens have the right to know the truth.
This issue must never be reduced to a partisan confrontation.
It concerns the capacity of the state, economic security and the right of every individual to have access to the money they have honestly earned.
Mickoski must not be held responsible for every problem inherited from previous governments, but no incumbent government can be exempted from accountability for its own actions. Previous administrations must not be forgotten, but the present government must not be granted immunity from criticism either. That is the principle of equal political and institutional accountability.
Ultimately, we must ask the question that connects all these cases:
Who supervises those responsible for supervising the banks? Who protects those who entrust their money to financial institutions? And who will be held accountable if the institutions have failed to do their job?
A country is not measured merely by the number of its banks, the size of its capital reserves or the volume of its financial transactions.
It is measured by how secure its citizens feel.
“A BANK MAY LOSE ITS OWNER. AN OWNER MAY LOSE HIS CAPITAL. BUT A STATE MUST NEVER LOSE THE TRUST OF ITS CITIZENS.”
Money can be earned again. Capital can be rebuilt. A bank can find a new owner. But once public trust has been lost, restoring it is infinitely more difficult.
THAT IS THE TRUE TEST OF STATESMANSHIP.
